What the Bank of Canada's September deliberations, Tiff Macklem's Halifax speech and TD's dissenting call tell us about the Oct. 28 decision.
A Macklem rate hike — unthinkable for most of the past year — has moved to the centre of Canada’s monetary policy debate after the Bank of Canada’s Governing Council warned that a sustained energy shock could force its hand before 2026 ends. The central bank left its policy rate unchanged at 2.25% in September, but the published summary of deliberations said that if high energy prices spill over into other goods and services, a “monetary response to prevent broad-based inflation” may be required this year.
That language marks a genuine shift. The last change to the overnight target came on Oct. 29, 2025, when the Bank cut by 25 basis points to 2.25%. Canadians carrying mortgages and other floating-rate debt have had nearly a full year of predictable borrowing costs since then — low, though nowhere near the emergency levels of the early pandemic period.
Why a Macklem Rate Hike Is Suddenly Being Priced In
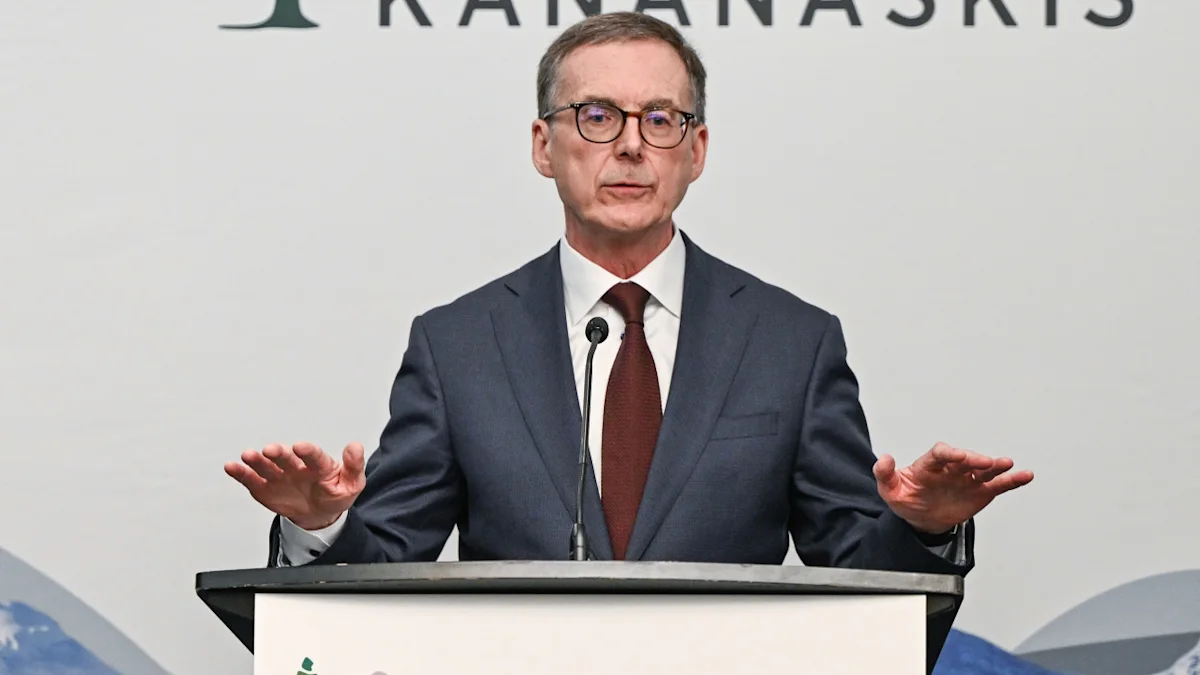
Speaking to business leaders in Halifax on Sept. 21, Governor Tiff Macklem framed the problem as a balancing act rather than a decision already made. “We don’t want to raise our policy rate and restrain growth if inflationary pressures are contained,” he said. “But nor do we want to be too slow to respond if inflationary pressures are becoming more persistent.”
Markets heard the second half of that sentence more loudly than the first. Pricing now implies at least one increase before year-end, and TD Economics notes that market expectations run as far as four quarter-point hikes by mid-2027. The Bank itself has committed to nothing for the Oct. 28 announcement, and TD’s own house view remains a hold for the balance of 2026 — a split we examined when the odds on an October move narrowed to roughly a coin flip.
Gasoline Up 22.8% While CPI Sticks at 3%
The arithmetic behind the Bank’s unease is straightforward. Statistics Canada reported that the consumer price index rose 3.0% year over year in August, matching July. Over the same window, gasoline prices jumped 22.8% — a single category doing an outsized share of the work in holding headline inflation a full percentage point above the Bank’s 2% target.
Tariffs dominate the headlines, but the Governing Council identified the conflict in the Middle East, and the war involving the United States there, as the dominant economic factor at play. Broader data on household pressure and demographic trends has been running alongside this story; our coverage of the latest Statistics Canada findings on slowing population growth offers context on the demand side of the same economy.
The US$40 Gap Between Oil’s Price and Its Fundamentals
Macklem’s Halifax remarks drew a careful line between noise and signal. A temporary spike in pump prices is something the Bank can “look through.” Persistently higher energy costs are not.
He set out the mechanics plainly. Under normal conditions, every 10% rise in the cost of oil adds roughly 0.2% to CPI. But with refining capacity damaged and global supply constrained, the gasoline-price shock Canadians are absorbing is unusually large relative to the underlying crude price. On the Bank’s own calculations, oil is trading approximately US$40 above where fundamentals suggest it should sit — the practical effect being a driver spending $140 at the pump on a fill that would otherwise cost $100. If crude holds near US$100 a barrel, Macklem warned, inflation will be pushed higher in the months ahead, and a policy adjustment may follow. The same oil-sensitivity argument underpinned our earlier report on how Macklem put a hike back in play on energy grounds.
How Fuel Costs Travel From the Pump Into Everything Else
The reason a central bank cares about gasoline is that fuel is an input cost across an enormous slice of the economy, not merely a line item in household budgets. Manufacturers ship materials. Farmers run machinery. Retailers move merchandise. Airlines buy jet fuel.
If those costs stay elevated long enough, businesses eventually attempt to recover them through prices. That is the spillover the Governing Council described, and it is what converts an energy shock into generalised inflation. The awkward outcome in that scenario is a central bank tightening policy even while economic growth remains weak — raising the cost of borrowing into a slowing economy because the alternative is letting price expectations drift.
Tariffs as a Supporting Actor, Not the Lead
Trade policy has not vanished from the picture; it has been demoted. The Bank expects Canada’s counter-tariffs — which largely target non-consumer goods where Canadian substitutes exist — to have only a modest direct effect on inflation. Even so, trade actions on both sides of the border add to business costs that can reach consumers over time.
The sharper risk, in Macklem’s framing, is to growth rather than prices. New U.S. tariffs touch roughly 5% of Canadian goods exported south. But if they stay in place, he cautioned, growth could be cut in half in the closing months of 2026, dropping below 1% on a GDP basis. That combination — firm inflation, soft output — is precisely what makes the October call difficult.
Why TD’s Andrew Hencic Calls a Hike “Premature”
Not everyone is persuaded. Andrew Hencic, director and senior economist at TD Economics, the research arm of TD Bank Group, argues that tightening now would be premature, and points to the Bank’s preferred core measures to make the case.
- Core inflation is near target: CPI-trim ran at 1.9% in August and CPI-median at 2.0%, both consistent with the Bank’s 2% objective.
- Growth is softening: momentum is weakening rather than overheating, which argues against adding restraint.
- The labour market still has slack: an economy with spare capacity transmits cost shocks into wages less readily.
- Yields are tightening conditions anyway: higher bond yields imported from the United States are doing some of the Bank’s work without a policy move.
On that reading, the energy shock is a relative price adjustment the Bank can absorb, and the September CPI print will matter more than any speech.
What a Quarter-Point Move Would Do to a $500,000 Variable Mortgage
For borrowers, the transmission is direct on the variable side. Variable rates track lenders’ prime rates, which move with the Bank’s policy rate. An illustrative calculation cited in reporting on the decision runs the numbers on a $500,000 adjustable-rate mortgage at 4.00% over a 25-year amortization, with payments of roughly $2,630 a month.
| Scenario | Change in monthly payment |
|---|---|
| One quarter-point increase | About $68 more per month |
| A full percentage point (four quarter-point moves) | About $278 more per month, or over $3,300 a year |
Holders of fixed-payment variable mortgages would see a different effect: the payment itself may not change, but a larger share of each instalment goes to interest rather than principal. These figures are a hypothetical illustration, not a quote or an offer, and individual terms vary by lender and contract.
Fixed Rates Are Already Moving Ahead of the Bank
Fixed-rate mortgages are priced off Government of Canada bond yields rather than the overnight rate, and yields have been climbing without any policy change at all. The 10-year yield sat at 3.87% on Sept. 18, up from a 52-week low of 3.04%.
Macklem himself noted that markets increasingly expect major central banks to raise rates, pulling Canadian yields higher in sympathy. The practical consequence is that posted fixed offers can shift well before the Bank acts — meaning the October decision may confirm a repricing that has already happened rather than trigger one.
Prima: A New Forecasting Model Debuts in the October MPR
Alongside the Oct. 28 rate announcement, the Bank will publish its quarterly Monetary Policy Report. This edition carries additional significance: it is the first built on Prima, a new forecasting model designed to help separate temporary inflation pressures from persistent ones.
That distinction is the entire argument of the moment. A model framed around telling a one-off energy shock apart from entrenched price pressure arrives at the precise juncture where the Governing Council is trying to make that call in public.
Two Dates to Watch: Oct. 19 CPI and the Oct. 28 Decision
The first marker is Oct. 19, when Statistics Canada releases September CPI. If price increases show signs of spreading beyond fuel into broader categories, the case for tightening strengthens considerably. If the pressure stays concentrated in gasoline, Hencic’s argument gains ground.
The second is Oct. 28 itself, when the rate call and the first Prima-based MPR land together. The Governing Council has been explicit that several outcomes remain possible: reopened shipping lanes could ease crude prices, while an escalating trade war could slow the economy enough to contain inflation on its own. Nothing is locked in, and the Bank has framed its own risk balance as conditional on events well outside Canadian control.
This article reports publicly available central bank commentary and economic data for general information. It is not financial advice; borrowers with questions about their own mortgage should consult a qualified professional.
Frequently Asked Questions
Has the Bank of Canada decided to raise rates?
No. The policy rate was held at 2.25% in September, and no decision has been announced for Oct. 28. The Governing Council said only that a monetary response may be required if energy costs spill into other goods and services.
Why is inflation at 3% if core measures are near 2%?
Headline CPI includes volatile components such as gasoline, which rose 22.8% year over year in August. The Bank’s preferred core measures, CPI-trim and CPI-median, strip out much of that volatility and ran at 1.9% and 2.0%.
When was the last change to the policy rate?
Oct. 29, 2025, when the Bank cut by 25 basis points to 2.25%. The rate has been unchanged since.
Would a hike affect fixed-rate mortgages?
Not directly. Fixed rates follow Government of Canada bond yields, which have already risen — the 10-year yield reached 3.87% on Sept. 18, up from a 52-week low of 3.04%.
What is Prima?
A new Bank of Canada forecasting model intended to distinguish temporary inflation pressures from persistent ones. The October Monetary Policy Report will be the first built on it.
The Brand Magazine Newsroom covers Canadian business, markets and policy news for brand builders and entrepreneurs. Newsroom reports are produced from published public sources such as company releases and government and regulator publications, and follow our Editorial Standards.